Roof Insurance Claims in Branson, Springfield & Southwest Missouri
Storm Damage? Get an Honest Roof Inspection From a Roofing Contractor With Real Insurance Adjusting Experience.
Before you file a roof insurance claim, know what you’re dealing with.
When hail or high winds hit your neighborhood, it can be difficult to know what to do next. Does your roof actually have storm damage? Is it serious enough to justify an insurance claim? What if the insurance adjuster says the damage is normal wear and tear? And what happens if the insurance estimate doesn’t include everything needed to complete the repairs?
At Bold Roofing, we help homeowners throughout Branson, Springfield, Ozark, Nixa, Republic, Hollister, and surrounding southwest Missouri communities answer those questions with professional roof inspections, detailed photographs, and accurate construction estimates.
What makes us different? Our owner, Mikel Miller, spent years working in the insurance industry as both an insurance agent and a licensed claims adjuster before transitioning into roofing.
We understand how roofs are built, how storm damage occurs, and how insurance companies typically document property damage.
Most importantly, we believe homeowners deserve accurate information before making expensive decisions.
Call or Text Bold Roofing: 417-222-7535
Free residential roof inspections and estimates are generally available throughout our service area.
From Insurance Agent to Catastrophe Adjuster to Roofing Contractor: Our Owner’s Story
Before founding Bold Roofing, owner Mikel Miller began his insurance career around 2006–2007 in Springfield, Missouri, working with State Farm.
He initially worked on the insurance agency side, helping customers with life, health, homeowners, and automobile insurance.
Although he enjoyed working with people and learning about insurance, he eventually realized that spending every day behind a desk wasn’t the career he wanted.
His father-in-law was already an experienced insurance claims adjuster and helped train him to enter the claims industry.
Mikel obtained his adjuster’s license and transitioned into property damage and catastrophe claims.
Over the years, his work took him across the country, including Texas, Florida, Georgia, North Carolina, South Carolina, Indiana, Kansas, and other states.
He and his family traveled extensively, sometimes living in different communities while he worked major storm events. During those years, they homeschooled their children and experienced firsthand the devastation hurricanes, tornadoes, hailstorms, and severe winds could cause.
His insurance experience included:
- Residential and commercial property damage
- Wind and hail claims
- Hurricane and tornado damage
- Fire and smoke damage
- Flood and water-related losses
- Vandalism claims
- Automobile damage and total losses
- Claims file review and quality assurance
- Training other insurance professionals
- Catastrophe and daily claims adjusting
Over the course of his career, Mikel estimates he has handled or reviewed more than 15,000 insurance claims.
Eventually, the constant travel became exhausting. He and his wife decided to return home to the Branson area, where their families had deep roots.
His wife attended Branson schools from kindergarten through graduation, and Mikel graduated from Hollister High School.
Today, they operate Bold Roofing in the same southwest Missouri communities they call home.
That background shapes how Bold Roofing approaches every storm-damaged property: inspect thoroughly, document accurately, communicate professionally, and tell the homeowner the truth.
Should You File an Insurance Claim for Roof Damage?
Our First Recommendation: Get Your Roof Inspected Before Making That Decision
One of the most common mistakes homeowners make after a hailstorm is assuming they should immediately file an insurance claim because their neighbors are getting new roofs.
But every roof is different.
Two houses on the same street may have different levels of damage because of roof age, shingle type, installation quality, roof orientation, slope, elevation, and the direction of the storm.
A newer roof may survive a storm with little functional damage, while an older or more vulnerable roof nearby may suffer substantial damage.
That’s why we recommend starting with a thorough inspection.
We examine the roof and surrounding exterior for evidence of storm damage, including:
- Hail impacts and potential shingle damage
- Wind-lifted, creased, torn, or missing shingles
- Damaged ridge caps and roof accessories
- Dented roof vents, flashing, and other metal components
- Damage to gutters and downspouts
- Signs of improper installation or previous repairs
- Deterioration unrelated to a recent storm
- Potential leak entry points
- Conditions that may affect repairability
We also consider available storm history, the property’s exposure, and other relevant evidence.
If we don’t believe your roof has significant storm damage, we’ll tell you.
You might need a small repair, routine maintenance, or nothing at all.
We would rather earn your trust by giving you an honest assessment than encourage you to pursue a claim that appears unlikely to result in a meaningful repair or replacement.
Can Filing a Roof Claim Affect Your Homeowners Insurance?
Homeowners sometimes hear that weather-related claims cannot affect their insurance premiums or coverage.
That statement is too broad.
The effect of a claim depends on factors including your state, insurer, policy, underwriting practices, claims history, and applicable law.
For example, multiple property claims within a relatively short period may affect how an insurer evaluates future coverage or renewal eligibility, even when one of those claims involves storm damage.
That does not mean you should avoid filing a legitimate claim. Insurance exists to protect you against covered losses.
It means you should make an informed decision based on actual damage, your deductible, your policy, and information from your insurer.
Bold Roofing can explain the roof’s physical condition and estimated repair costs. Your insurance company or a properly licensed insurance professional should answer questions about coverage, premiums, claim history, and policy consequences.
Our Roof Insurance Claim Inspection Process
Step 1: We Inspect Your Roof With Fresh Eyes
If another roofing contractor or insurance adjuster has already inspected your home, that’s perfectly fine.
We actually prefer to perform our own inspection before reviewing their findings.
Why?
Because we want an independent assessment based on what we observe, rather than allowing someone else’s conclusions to influence our inspection.
We examine the roof and accessible exterior areas, document relevant conditions, and identify potential storm-related damage.
We may also review:
- Available historical hail and wind reports
- The reported date of loss
- The direction of the storm
- Roof age and shingle type
- Roof pitch and exposure
- Elevation and surrounding terrain
- Visible deterioration or installation problems
- Whether a roofing product may be discontinued or difficult to match
Our objective is to develop a clear picture of the roof’s condition.
Step 2: We Create a Detailed Photo Report
In the insurance industry, photographs are one of the most important forms of property damage documentation.
But simply taking hundreds of pictures doesn’t necessarily make a strong report.
The right photographs matter more than the number of photographs.
Many contractors focus almost entirely on close-up pictures of individual damaged shingles.
We take those pictures, too, but we also emphasize overview photographs.
An overview image can show the location and distribution of damage across an entire roof slope. Close-up images can then provide additional detail.
Together, they give the viewer a much clearer understanding of the property.
Depending on the project, our reports may include:
- Full roof-slope overviews
- Close-up photographs of visible damage
- Photos of roof accessories and exterior components
- Images identifying specific slopes and elevations
- Measurements and relevant construction details
- Available supporting weather information
- Written explanations of observed conditions
We organize the information in a format familiar to insurance professionals and provide the homeowner with a copy.
The report is yours to keep, even if you don’t hire Bold Roofing.
Step 3: We Prepare a Construction Estimate
If repairs or replacement are needed, we prepare an estimate for the construction work.
For insurance-related projects, we frequently use Xactimate, an estimating platform commonly used throughout the property insurance industry.
Using a familiar estimating format can make it easier for contractors, homeowners, and insurance representatives to compare the proposed repair scope.
Our estimate may identify items such as roofing materials, labor, tear-off and disposal, flashing, ventilation, gutters, and other construction components needed for the project.
We focus on the actual work required to restore the property—not on promising what an insurance company will pay.
Step 4: We Can Attend the Insurance Adjuster’s Property Inspection
If the homeowner requests it, Bold Roofing can meet the insurance company’s adjuster at the property.
Our approach is different from the confrontational style some homeowners may have experienced.
We don’t believe an inspection should become an argument.
Insurance adjusters have demanding jobs, especially following widespread storms. Many inspect multiple properties every day under difficult conditions.
We prefer to make their job easier by being prepared, professional, and helpful.
During a joint inspection, we may:
- Point out physical damage we documented
- Identify specific roof slopes or exterior components
- Share photographs and measurements
- Explain construction methods or material requirements
- Answer technical roofing questions
- Provide relevant supporting documentation
- Assist with safe access or measurements when appropriate
Our goal is respectful communication and a complete, accurate understanding of the property’s physical condition.
We don’t need to be aggressive to be effective.
And we don’t need to promise a claim approval to provide homeowners with valuable service.
The insurance company makes its own coverage and payment decisions.
Step 5: We Review the Proposed Construction Scope
After an insurance inspection, a homeowner may receive an estimate describing the work the insurer has included.
Sometimes that estimate closely matches the construction work needed.
Other times, there may be differences involving measurements, materials, flashing, ventilation, gutters, or other building components.
We can compare the proposed construction scope with our own inspection findings and explain differences involving the physical repair work.
When appropriate, we can provide supplemental photographs, measurements, and construction estimates for the homeowner or insurance company to review.
We do not interpret policy coverage on the homeowner’s behalf, negotiate insurance settlements, or represent homeowners as public adjusters.
Our role remains that of the roofing contractor documenting and estimating the work.
Step 6: We Complete the Roofing Project
Once the homeowner has authorized the work and the project is scheduled, our focus shifts to delivering a professional installation.
Our typical roof replacement process includes:
- A preconstruction discussion and homeowner preparation instructions
- A dedicated on-site project manager
- Removal of the existing roofing materials as specified
- Inspection of exposed roof decking
- Installation of appropriate underlayment and roof components
- Attention to flashing, ventilation, and manufacturer installation requirements
- Photo documentation throughout the project
- Cleanup and magnetic nail sweeps
- A final project review
We can provide homeowners with a convenient online photo gallery to follow progress, along with electronic paperwork and payment options.
Our qualifying residential roofing projects include a five-year workmanship warranty, separate from applicable manufacturer material warranties.
Real Branson Roofing Project: An Older Roof With Hail Damage and Solar Panels
Bird Road, Branson, Missouri
A homeowner on Bird Road in Branson had a roof that was already showing its age.
The property also had solar panels installed on the front portion of the roof.
An insurance inspection had resulted in a disagreement about the cause of certain visible conditions. The insurer initially characterized the roof conditions as wear and tear or blistering rather than covered storm damage.
When Bold Roofing inspected the property, we documented significant hail-related damage on a rear roof slope, away from the solar panels.
Instead of relying only on close-up photographs, we examined the overall pattern of damage.
We also gathered historical storm information and evaluated whether the observed damage was consistent with the direction of the reported hailstorm.
We assembled photographs, a construction estimate, and supporting weather information into a report for consideration.
Following that additional documentation, State Farm revised its position and included approximately 60% of the roof in its payment determination.
The homeowner chose to pay the remaining portion out of pocket so the entire roof could be replaced together.
The homeowner was pleased with the outcome, especially because they had initially expected little or no insurance contribution.
Why this project matters: An older roof can have both preexisting wear and legitimate storm damage. A careful inspection helps distinguish those conditions rather than assuming everything is one or the other.
This is one example of an actual project, not a promise that another insurer will reach the same decision.
Real Branson Roofing Project: Bedroom Leak Leads to a Full Roof Replacement
Cramer Family — Emory Creek, Branson, Missouri
The Cramer family discovered a roof leak in a particularly unpleasant way.
Water was entering their bedroom near their bed.
During the night, they climbed into the attic to investigate and discovered that the water was coming through the roof.
They contacted Bold Roofing for help.
We performed temporary repairs to address the immediate leak and inspected the roof to identify the underlying problems.
During our inspection, we documented widespread hail damage that the family had not previously recognized.


We later met with their Farm Bureau insurance adjuster and shared the physical damage findings.
After the inspection, the insurer approved replacement of the roof and gutters.
The Cramers chose to change their roof color to Williamsburg Gray, giving the home a fresh appearance.
During the project, we also addressed an important construction issue: a roof-to-wall intersection had been installed without the necessary flashing.
We installed appropriate flashing, including step flashing and related water-diversion details, to improve protection at that vulnerable area.
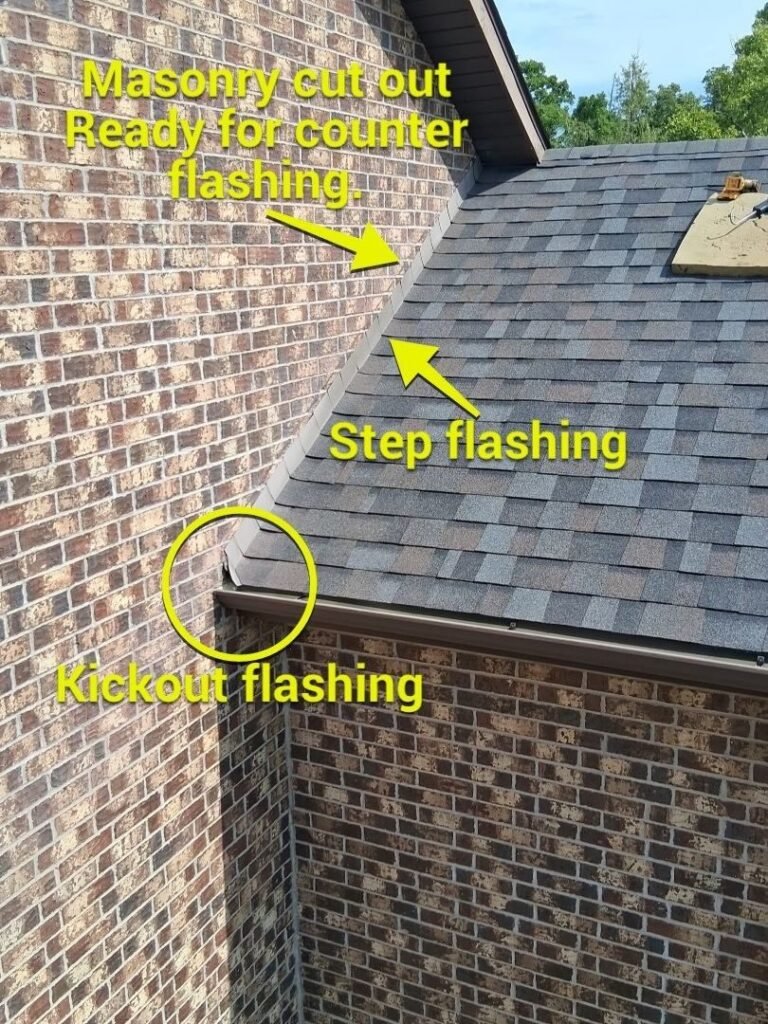
The finished project wasn’t just about replacing storm-damaged shingles. It was also an opportunity to correct a condition that could contribute to future water intrusion.
What the Homeowner Said
“Bold Roofing has done work for me a few times. Each time they show they care. They go above the average standard of service. They are kind, have great competitive rates and most importantly, they do what they say they will do.
I highly recommend Bold Roofing for your residential or commercial needs.”
Katrina Cramer, Google Review, March 29, 2025
Why this project matters: When a roof leaks, the most important question isn’t simply whether the shingles need replacing. It’s identifying how water is entering the structure and ensuring the necessary construction details are addressed.
See the full Cramer family project on our Branson roofing page.
What If Your Insurance Company Says Your Roof Damage Is Just Wear and Tear?
This is one of the most common concerns we hear from homeowners.
Sometimes the insurance company is correct.
Roofs deteriorate naturally over time, and not every missing granule, blister, crack, or worn shingle is evidence of storm damage.
Other times, there may be legitimate storm damage mixed with ordinary aging.
The key is evaluating the evidence.
For example, a hailstorm may affect one roof slope more severely than another because of the direction of the storm.
A roof can also have an installation defect or manufacturing-related deterioration unrelated to a recent weather event.
We look at the overall pattern, location, and characteristics of the damage before reaching a construction-related conclusion.
If we disagree with another assessment of the roof’s physical condition, we explain why and provide supporting photographs and observations.
We don’t guarantee that an insurer will change its decision, but homeowners deserve an accurate assessment of the condition of their property.
Common Roof Insurance Claim Questions
Will homeowners insurance pay for an old roof?
Possibly. Roof age alone does not automatically determine whether storm damage is covered.
Coverage depends on your specific policy, the cause of loss, applicable exclusions, and the insurance company’s determination.
Some policies provide replacement cost coverage, while others use actual cash value, roof payment schedules, or other limitations.
An older roof may have legitimate storm damage, but the amount an insurer pays can vary substantially.
Bold Roofing can evaluate the physical damage and estimate repair or replacement costs. Your insurance company should explain the coverage provisions and payment calculation that apply to your policy.
Should I call my insurance company or a roofer first after a hailstorm?
If you suspect roof damage but don’t have an urgent emergency, a professional roof inspection can help you understand the condition of the roof before deciding whether to submit a claim.
However, if your home has active water intrusion or substantial damage, promptly protect the property from further damage when safe and notify your insurer as required by your policy.
Do not delay a necessary claim or required notice solely to wait for a roofing inspection.
Does hail damage always mean I need a new roof?
No.
The extent of hail damage depends on the roofing material, storm conditions, age, installation, and other factors.
Some roofs require only limited repairs. Others may have widespread damage that makes replacement the appropriate construction solution.
We inspect first and recommend work based on the conditions we find.
What if my insurance company denies my roof claim?
A denial does not automatically mean the roof is undamaged, but it also doesn’t mean the insurance company made a mistake.
You can ask your insurer for an explanation of its decision.
Bold Roofing can provide an independent roofing inspection, photographs, and a construction estimate documenting the physical conditions.
For disagreements involving policy interpretation, coverage, or claim settlement, consult your insurer, a properly licensed public adjuster where permitted, or an attorney.
Can Bold Roofing meet my insurance adjuster?
Yes.
At the homeowner’s request, we can attend a property inspection to identify observed damage, answer construction questions, provide measurements, and share relevant documentation.
We work professionally and respectfully with insurance representatives.
Do you use Xactimate?
Yes. For many insurance-related construction projects, we use Xactimate to prepare detailed estimates.
This can help present the proposed construction work in a format familiar to many property insurance professionals.
Using Xactimate does not guarantee insurance approval or payment.
What if the insurance estimate is lower than my roofing estimate?
There may be differences in quantities, materials, labor assumptions, or the construction items included.
We can explain our estimate and document the work we believe is necessary to complete the project properly.
The insurance company determines what it will pay under the policy. The homeowner remains responsible for understanding the policy and any amounts not paid by insurance.
Can I choose my own roofing contractor?
Generally, homeowners can choose the roofing contractor they prefer, subject to any applicable policy provisions or program requirements.
You do not have to assume that the first contractor recommended to you is your only option.
Confirm any specific requirements with your insurance company.
Do you help with wind damage and missing shingles?
Yes.
We inspect roofs for wind-related damage, including missing, torn, creased, or displaced shingles and affected roofing accessories.
We can also provide estimates for repairs or replacement where appropriate.
Are roof inspections free?
For most residential properties within our southwest Missouri service area, Bold Roofing provides roof inspections and estimates at no charge.
Unusually extensive, specialized, or formal reporting services may involve a fee, which we would discuss before proceeding.
Can you inspect my roof even if I already have an insurance estimate?
Absolutely.
We often inspect properties after another contractor or an insurance adjuster has already visited.
We prefer to complete our own inspection first, then compare the documented physical conditions and construction scope with the information you already have.
Can you work with me if I live out of state?
Yes.
We regularly work with homeowners, property managers, and vacation-property owners who cannot be present for every inspection or construction visit.
We offer digital paperwork, electronic payments, project photographs, and convenient communication throughout the process.
Local Roof Insurance Claim Inspections Across Southwest Missouri
Bold Roofing is locally based in Branson, Missouri, and serves homeowners and property owners throughout the surrounding region.
Our primary service communities include:
- Branson, MO — Roof leak inspections, hail damage documentation, wind damage, roof replacement, and gutters
- Springfield, MO — Residential storm damage inspections, insurance-related construction estimates, and roof replacements
- Ozark, MO — Hail and wind damage roofing inspections and replacement projects
- Nixa, MO — Roof condition assessments, repairs, and residential roof replacement
- Republic, MO — Storm restoration, roofing, gutters, and projects requiring solar panel coordination
- Hollister, MO — Roof inspections, leak repairs, and storm-related roofing work
- Branson West and Kimberling City, MO — Residential and vacation-property roofing services
- Forsyth and surrounding Taney County communities — Roof repairs, inspections, and replacements
Our experience with southwest Missouri weather, roofing systems, and local construction conditions helps us provide relevant information for property owners throughout the region.
Whether your roof was damaged in a major hailstorm or you’re simply uncertain about its condition, we can help you understand what the roof needs.
Why Homeowners Choose Bold Roofing for Storm-Damaged Roofs
Insurance Industry Experience
Our owner worked in insurance claims before entering the roofing industry. That experience helps us understand how to document property damage and prepare organized construction estimates.
Honest Inspections
We don’t believe every roof needs replacing. If a repair is appropriate or the roof is in good condition, we’ll explain that.
Detailed Photo Documentation
We provide organized photographs and findings so homeowners can understand what we observed and retain the information for their records.
Professional Communication
We prefer cooperation over confrontation when communicating with insurance representatives.
Roofing Knowledge Beyond Shingles
We look at flashing, ventilation, decking, roof accessories, gutters, and other components that affect the performance of the roofing system.
Local Accountability
We’re a southwest Missouri roofing company with family roots in the Branson area, not an out-of-state storm-chasing operation.
A More Convenient Roofing Experience
With electronic paperwork, online payments, and project photo updates, we make it easier for busy homeowners and out-of-state property owners to manage their roofing projects.
Helpful Roofing Guides
- Hail Damage Roof Insurance: How to Get a Fair Claim Payout
- Class 4 Shingles in Missouri: Are They Worth It?
- Should I Repair or Replace My Roof? Honest Advice From a Springfield, MO Roofing Contractor
- The Engineer Card: How Insurance Companies Hire “Experts” to Deny Your Claim
Get Answers Before You Make a Roof Insurance Claim Decision
If your neighborhood recently experienced hail or high winds, you don’t have to guess whether your roof was damaged.
And you don’t have to rely solely on what another homeowner, a salesperson, or a social media post tells you.
Start with a professional inspection and a clear explanation of what we find.
At Bold Roofing, our goal is simple:
Tell you the truth about your roof, document the conditions accurately, and recommend the construction work that actually makes sense.
Whether your roof needs a small repair, a full replacement, or no work at all, we want you to have the information necessary to make a confident decision.
Call or Text Bold Roofing Today
Serving Branson, Springfield, Ozark, Nixa, Republic, Hollister, Branson West, Kimberling City, and surrounding southwest Missouri communities.
Free residential roof inspections and estimates in our normal service area.
Out with the OLD roof. In with the BOLD roof!
Important Insurance and Legal Disclosure
Bold Roofing is a roofing contractor, not a public adjusting firm. Although our owner has professional experience as a licensed insurance claims adjuster, Bold Roofing does not provide public adjusting services to homeowners.
Our services are limited to roofing and construction inspections, physical damage documentation, repair recommendations, construction estimates, and related contractor communications.
We do not represent policyholders in insurance claim negotiations, interpret insurance policies on their behalf, determine coverage, promise claim approval, or negotiate insurance settlements.
Insurance coverage, claim payments, deductibles, policy limitations, premiums, and underwriting decisions are determined by the applicable policy, insurance company, and governing law. For questions concerning those matters, contact your insurance company, licensed insurance representative, properly licensed public adjuster, or attorney.
Examples of past projects are provided for informational purposes only. Results vary by property, insurer, policy, and circumstances.